
Home loans
Saving for the down payment: the arithmetic of the 20%, stamp duty, and deposits vs gold
Why the RBI's loan-to-value slabs mean your share can be 10%, 20% or 25% of the price, why stamp duty pushes the real cash target higher, and how a fixed deposit and gold compare when you need a known sum on a known date.
Home loans for NRIs: who can lend, repaying from NRE or NRO, and the power of attorney
What the FEMA Borrowing and Lending Regulations, 2018 and the RBI's Master Direction say about home loans to NRIs and OCI cardholders, the accounts you can repay from and why it matters at resale, how a power of attorney signed abroad is stamped, and the EMI on ₹60 lakh over 15 years.
The Key Facts Statement: what your lender must show you before you sign a home loan
Since October 2024, every bank and housing finance company must give you a standard Key Facts Statement before you sign: the all-in APR, every fee and the repayment schedule. What it must contain, the fees it rules out, and how the APR can change which offer is cheaper.
Credit score and your home-loan rate: how lenders price the spread over repo
Your home-loan rate is the repo rate plus a spread, and part of that spread is priced on your credit risk. What RBI rules allow banks to change and when, your rights to a free credit report and quick corrections, and what half a point of spread costs on ₹50 lakh.
Loan against property vs home loan: how rates, borrowing limits, prepayment and tax compare
Both are secured on a house, but RBI rules on loan-to-value, rate resets and prepayment apply differently, and the Income-tax Act, 2025 gives relief by use of money, not loan label. With the EMI and tax arithmetic on ₹30 lakh over 15 years.
Your floating rate went up: RBI's reset rules let you choose EMI or tenure, and maybe fixed
After the repo rate rose to 5.50%, your lender must let you pick a higher EMI, a longer tenure or a mix, and must not stretch the loan into negative amortisation. Since October 2025 the switch to a fixed rate is the lender's option. A ₹50 lakh example shows what each choice costs.
Closed your home loan? RBI's 30-day rule for getting your title deeds back, and ₹5,000 a day if late
Lenders must return your original property papers and clear their charge within 30 days of closure, or pay ₹5,000 for every day of delay that is their fault. Who the rule covers, how to count the days, what happens if papers are lost, and where to complain.
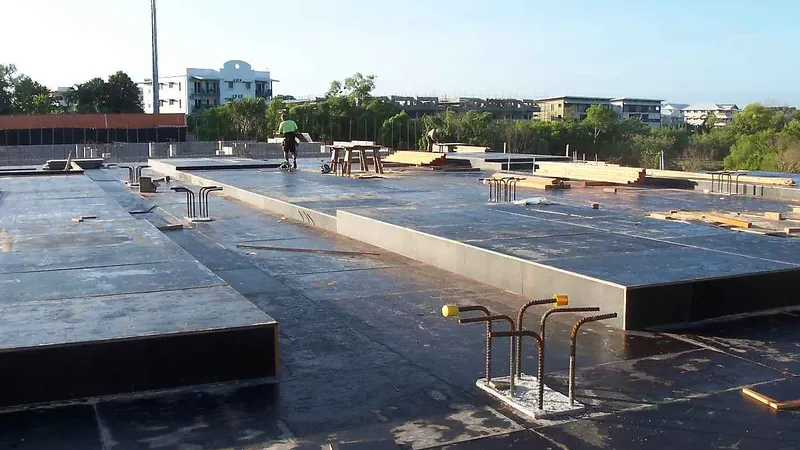
Construction-linked home loans: how banks release the money for an under-construction flat, stage by stage
Your bank pays an under-construction loan in tranches tied to the building's progress, not in one go. The RBI and NHB rules behind that, how a tranche is released, how RERA's 70% project account runs alongside it, and a worked example of how the split between your money and the bank's changes the interest bill.
PMAY-U 2.0 interest subsidy: who qualifies, what the ₹1.8 lakh is really worth, and how to claim it
The guideline's actual caps on income, loan, house value and carpet area; why ₹1.8 lakh is worth about ₹1.4–1.5 lakh today; what five yearly instalments do to your EMI; and the steps your lender must follow to claim it.
How banks work out your home-loan eligibility, and why two lenders quote different amounts
Your sanction is the lower of two limits: what your income can carry after existing EMIs, which is lender policy, and RBI's loan-to-value cap on the property. A worked example with two lenders shows how FOIR, tenure and rate move the number by lakhs, and what to compare once offers arrive.
Co-owner, co-borrower, co-applicant: who can claim home-loan tax deductions under the Income-tax Act, 2025
Banks say co-applicant, the sale deed says co-owner, the loan agreement says borrower. How sections 20, 22, 24 and 123 of the new Act decide who gets the interest and principal deductions, and what a couple on an ₹80 lakh loan can claim under the old and new regimes.
Home-loan balance transfer after the repo hike: the break-even sum and the fees people miss
With repo at 5.50%, the spread your lender charges over the benchmark decides what you pay. This explainer shows how to work out the break-even month of a balance transfer, which fees to count (including state stamp duty), and what RBI rules say about foreclosure charges and the Key Facts Statement.